Niagara communities
Lincoln, Beamsville, Vineland and Jordan Mortgage Broker
Subdivisions in Beamsville, village homes in Vineland and Jordan, and Benchland properties among the vineyards. What the $695,000 benchmark costs, and how lenders treat the rural side of Lincoln.
Reviewed November 13, 2026 · Indicative figures, OAC
Lincoln in four numbers
- Benchmark price
- $695,000
- Property tax rate (approx.)
- 1.18%
- Minimum down at benchmark
- $44,500
- Ontario LTT at benchmark
- $10,375
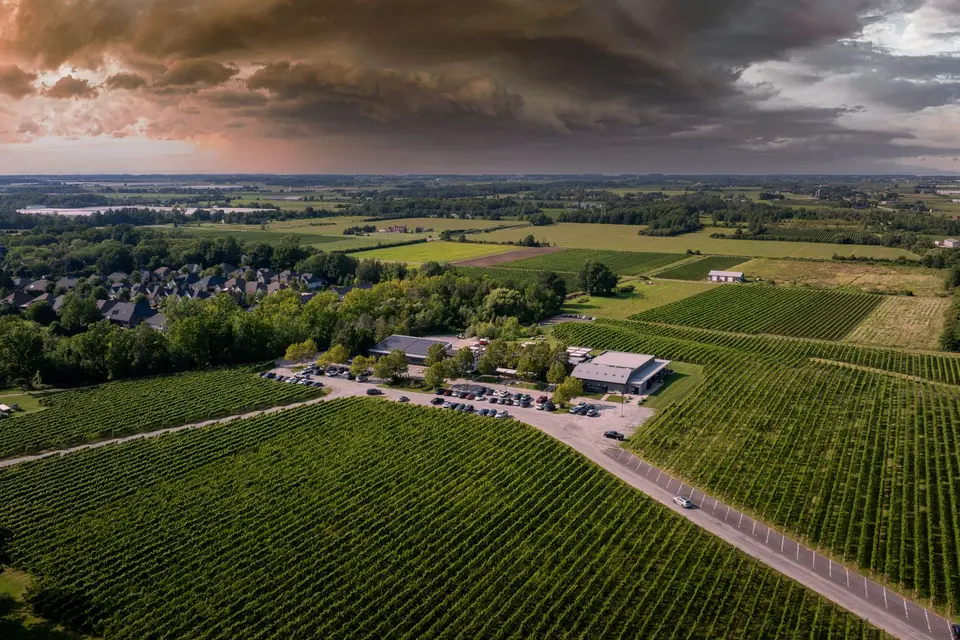
The Town of Lincoln runs from the Lake Ontario shore up over the escarpment, between Grimsby and St. Catharines. It is really a group of communities: Beamsville, the largest, with most of the town's subdivisions; Vineland and Jordan, smaller villages in wine country; and a large rural area of orchards, vineyards and Benchland estates. The composite benchmark is about $695,000.
The residential tax rate is approximately 1.18%, about $8,201 a year or $683 a month at the benchmark. That estimate is for budgeting only; confirm the current rate and your property's assessment with the Town of Lincoln.
Two very different kinds of Lincoln file
Town properties: Beamsville, Vineland, Jordan
Homes on municipal water and sewer in Beamsville and the villages are standard residential files. Buyers are often families moving along the QEW from Hamilton, Burlington or Grimsby looking for more house for the money, and couples who work in St. Catharines. These files are mostly about down payment, income and the right rate tier, and our commuter guide covers selling elsewhere and buying here.
Rural and Benchland properties
Away from the villages, much of Lincoln is agricultural, and many homes there run on private services. This is where Lincoln mortgages get technical:
- Water. Some properties have drilled or dug wells; others rely on a cistern, a tank filled by rain or hauled water. Lenders typically want a potable water test for bacteria, and for wells sometimes a flow test, before funding.
- Septic. A septic inspection ($400 to $800) is a normal condition. An old or failing system can lead to a holdback or a decline.
- Acreage. Many A-lenders value the house and up to about 10 acres; land beyond that, and outbuildings, get little or no value. A 25-acre parcel can appraise for less lending value than its price suggests.
- Zoning and the escarpment. Agricultural zoning and properties inside the Niagara Escarpment Commission's area add planning checks. Check the current zoning by-law and NEC rules before you plan additions or a second dwelling.
Our rural cistern, well and septic guide lists the tests and timing.
Hobby vineyards and small farms
Lincoln is the heart of the Beamsville Bench and Twenty Valley wine country, and some buyers want a house with a few rows of vines or an orchard. The line lenders draw is between a home on a reasonable lot, which default insurers and A-lenders finance as residential, and an income-producing farm, which needs agricultural lending from lenders such as Farm Credit Canada or a credit union. If farm income is part of your plan, or the parcel is large, expect a different lender, a larger down payment and a farm appraisal. The vineyard and hobby farm guide explains where that line usually falls.
Which lenders fit Lincoln
Big banks handle town properties well. Rural files are where lender choice matters most: some Ontario credit unions, including Niagara-based ones, and some monoline lenders are more comfortable with cisterns, septic and larger lots, while others decline them or cap the loan-to-value. Applying to the wrong lender first wastes the financing condition period. On prime files the lender pays the brokerage, so there is no fee to you; any compensation is disclosed in writing before you sign. For the trade-offs, read monoline vs. credit union. If your Beamsville purchase is a newly built home, the 30-year insured amortization is open to you even as a repeat buyer, and the new-build mortgage page covers closing dates, deposits and the final appraisal.
Closing costs and qualifying income at $695,000
Worked example: a $695,000 home in Lincoln
Minimum down, 5-year insured fixed at 4.29% (indicative, OAC), property tax at about 1.18%, $125 a month for heating. Left: a repeat buyer of a resale home at 25 years. Right: a first-time buyer at 30 years with the land transfer tax refund. Rural properties add water, septic and sometimes appraisal costs on top.
| Item | Repeat buyer, 25 years | First-time buyer, 30 years |
|---|---|---|
| Purchase price | $695,000 | $695,000 |
| Minimum down payment (5% of $500,000 + 10% of $195,000) | $44,500 | $44,500 |
| Mortgage before insurance (93.60% loan-to-value) | $650,500 | $650,500 |
| Default insurance premium | 4.00% = $26,020 | 4.20% = $27,321 |
| Insured mortgage | $676,520 | $677,821 |
| 8% Ontario PST on premium (cash) | $2,082 | $2,186 |
| Ontario land transfer tax | $10,375 | $6,375 (after $4,000 refund) |
| Municipal land transfer tax | $0 | $0 |
| Legal, title insurance and disbursements (budget) | $1,850 | $1,850 |
| Cash needed on closing | $58,807 | $54,911 |
| Monthly principal and interest at 4.29% | $3,666 | $3,335 |
| Monthly property tax (about 1.18%) | $683 | $683 |
| Heating allowance | $125 | $125 |
| Monthly housing cost | $4,474 | $4,143 |
| Payment at the 6.29% stress-test rate | $4,446 | $4,155 |
| Household income needed at 39% GDS | $161,666 | $152,735 |
Income figures assume no other debts. On a rural purchase, budget a further $400 to $800 for the septic inspection and the cost of water testing.
Run your own scenario in the payment and closing cost calculator or the stress-test calculator. Neighbouring options: Grimsby, St. Catharines and West Lincoln.
Frequently asked questions
How much do I need down on a $695,000 home in Beamsville?
The minimum is 5% of the first $500,000 plus 10% of the remaining $195,000, which is $44,500. Cash to close with that minimum is about $58,807 for a repeat buyer, including PST on the insurance premium, $10,375 land transfer tax and about $1,850 in legal costs.
Can I get a mortgage on a Lincoln home with a cistern?
Yes, many lenders finance cistern properties, usually with a potable water test as a condition. Some lenders are more comfortable with private water systems than others, so choosing the lender before you apply matters.
Will a bank finance a house on 20 acres in Lincoln?
Many A-lenders value the house and up to about 10 acres, giving little or no value to the extra land or outbuildings. A larger parcel can still be financed, but the down payment may need to be higher, and an income-producing farm needs an agricultural lender.
What is the property tax rate in Lincoln?
Approximately 1.18%, about $683 a month on a $695,000 home. Confirm the current rate and your assessment with the Town of Lincoln before relying on it.
Is a hobby vineyard treated as a farm by lenders?
It depends on size and income. A home on a modest lot with some vines is usually residential. If the property produces meaningful farm income or the land is large, lenders often treat it as agricultural, which means a different lender and appraisal.
Pre-approval & rate review
Get your Niagara mortgage numbers checked
Tell us where you are buying or what you owe. We reply by email, usually within one business day, with options from across the lender tiers.
- A licensed advisor reviews your numbers against A-lenders, Ontario credit unions and alternative lenders.
- Rate holds of up to 120 days on purchases and renewals (lender-dependent).
- On prime files the lender pays the brokerage, so there is no fee to you; any fee on alternative or private files is disclosed in writing first.
- Nothing goes to a lender or credit bureau until you say so.
Prefer email? Write to hello@mortgageniagara.com.