Niagara property specialists
Mortgages for Century Homes and Wartime Houses in Niagara
Older Niagara homes are some of the region's best value, but their wiring, plumbing and oil tanks tend to surface at the insurance company first and the lender second. Here is what gets flagged and how to finance the fix into your mortgage.
Reviewed November 13, 2026 · Indicative figures, OAC
Niagara's older housing stock
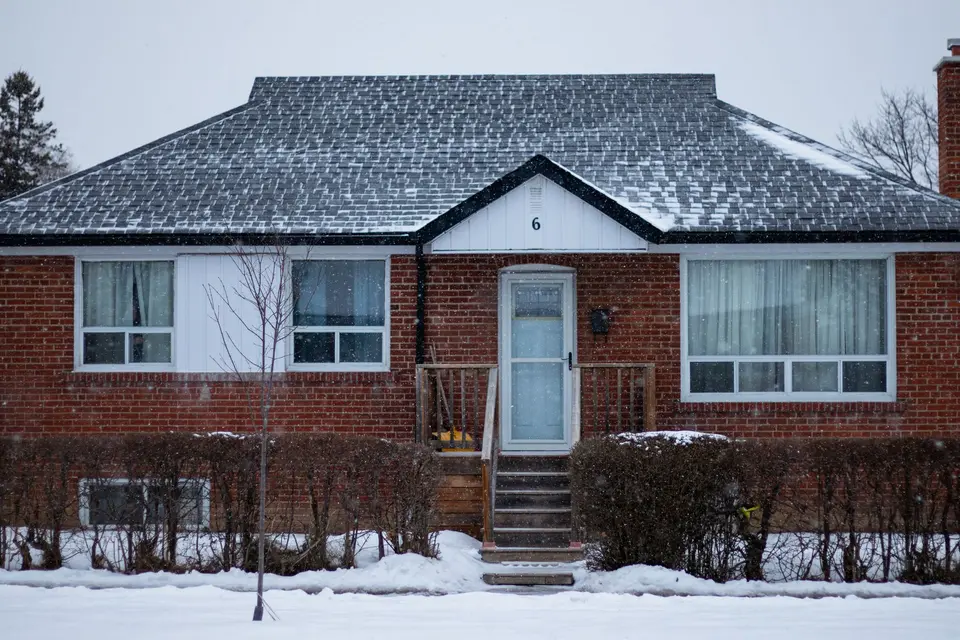
Niagara has a lot of old houses. Merritton and the streets around downtown St. Catharines, old Glenridge, Thorold's downtown, central Welland, Chippawa and the older blocks of Niagara Falls, Port Colborne's west side and Niagara-on-the-Lake's Old Town all have homes from the late 1800s and early 1900s. Scattered through St. Catharines, Welland, Niagara Falls and Port Colborne are also wartime houses: small storey-and-a-half homes built quickly in the 1940s for workers and returning veterans, often around 700 to 1,000 square feet on modest lots.
These houses are often the most affordable detached homes in their towns, which is why first-time buyers find them. The mortgage itself is usually ordinary. The complications come from what is inside the walls.
- Insured LTV if insurable
- Up to 95%
- Home inspection (typical)
- $450–$650
- FTHB land transfer tax refund
- Up to $4,000
- FTHB insured amortization
- 30 years
What gets flagged, and by whom
| Issue | Who usually raises it | Typical requirement |
|---|---|---|
| Knob-and-tube wiring | Home insurer | Electrician's report or replacement before coverage, or within a set time |
| 60-amp or fuse panel | Home insurer | Upgrade to a modern breaker panel |
| Galvanized or lead water pipes | Insurer, inspector | Replacement plan; lead service line checked with the municipality |
| Oil tank (in basement or buried) | Insurer, lender | Inspection certificate, age proof, or removal; buried tanks may need environmental review |
| Vermiculite insulation | Inspector | Testing for asbestos before any disturbance |
| Rubble stone or block foundation, wet basement | Appraiser, inspector | Repair estimate; lender may want work completed |
| Heritage designation or district | Lawyer, municipality | Limits on exterior changes; confirm with the municipality |
Why insurance matters to the lender
No lender will fund a mortgage without proof of home insurance naming it as loss payee. If the insurer will not bind a policy because of knob-and-tube wiring or an old oil tank, the deal stalls days before closing. Get an insurance quote with full disclosure of wiring, plumbing, heating and roof age during your conditional period, not after.
What the appraiser does
Appraisers value older homes against similar older homes, so age by itself is not a problem. Deferred maintenance is. A sagging porch, an obvious roof leak or a basement with standing water may lead to a lower value or a condition that work be done before funding.
Heritage properties
Some homes in Niagara-on-the-Lake's Old Town and other areas are designated under the Ontario Heritage Act or sit in a heritage district. That rarely affects the mortgage directly, but it can limit renovations and windows and add approvals. Your lawyer can search for designation; confirm details with the municipality.
Financing the fix: purchase plus improvements
A purchase-plus-improvements mortgage lets you add renovation costs to an insured or conventional purchase mortgage. The lender approves the work from a contractor's quote, the appraiser values the home as improved, and the renovation money is held back by your lawyer until the work is done and inspected. Many lenders cap the improvement amount as a share of the as-improved value, and the cap varies by lender and insurer. Full details in our purchase plus improvements guide.
Worked example: a Merritton century home with knob-and-tube, $485,000
First-time buyers find a 1910 brick home in Merritton, St. Catharines, listed at $485,000. The inspection finds active knob-and-tube wiring, a 60-amp panel and galvanized supply pipes. Their insurer will cover the home only if the wiring is replaced within a short window. A contractor quotes $40,000 for rewiring, a new 200-amp panel and new supply plumbing. The appraiser values the home as improved at $525,000.
| Item | Without improvements | With $40,000 improvements |
|---|---|---|
| Price plus improvements | $485,000 | $525,000 |
| Minimum down payment | $24,250 | $27,500 |
| Base loan | $460,750 | $497,500 |
| Premium (4.00% + 0.20% for 30 years) | $19,351.50 | $20,895 |
| Total mortgage | $480,101.50 | $518,395 |
| Monthly payment at 4.29% | $2,362 | $2,551 |
The down payment on $525,000 is 5% of $500,000 ($25,000) plus 10% of $25,000 ($2,500) = $27,500, just $3,250 more than on the price alone. The 8% PST on the $20,895 premium, $1,671.60, is paid in cash on closing. For about $188 a month more, the house is rewired and replumbed with no credit card or line of credit at 10%-plus.
Land transfer tax is calculated on the $485,000 price: $6,175, less the first-time buyer refund of up to $4,000, leaves $2,175. Property tax at St. Catharines' approximate 1.26% rate is about $509 a month on the purchase price; confirm the actual bill.
The $40,000 is held by the lawyer and released after the work is finished and the lender's inspector confirms it. The buyers need the contractor to start promptly, and sometimes need cash or a short bridge to pay deposits before the holdback is released.
Which lender tier fits
| Situation | Usual fit |
|---|---|
| Older home, updated systems, insurable | A-lender, insured or conventional, no special conditions |
| Needs rewiring, plumbing or a furnace swap | A-lender with purchase plus improvements |
| Major structural work, home not livable | Private or B-lender short term, then refinance after renovation |
| Buried oil tank or environmental concern | Lender-dependent; often requires removal and a clean report first |
First-time buyers should also read our first-time buyer guide for the FHSA, Home Buyers' Plan and land transfer tax refund.
Documents for an older-home file
- Home inspection report, with photos of the electrical panel, wiring, plumbing and heating.
- Insurance quote or binder, with wiring, plumbing, heating and roof ages disclosed.
- Contractor quotes for any work you want to finance, ideally from licensed electricians and plumbers.
- Oil tank certificate or removal records, if any.
- Your income and down payment documents as for any purchase.
Steps to buy an older Niagara home
- Get pre-approved with room for improvements. We can pre-qualify you for the price plus a renovation budget. Start at pre-approval.
- Make the offer conditional. Financing, inspection and insurance; your lawyer drafts the conditions.
- Inspect with an older-home specialist. Ask them to look at wiring type, panel size, supply pipes, oil tanks, insulation and foundation.
- Call the insurer immediately. Find out what they require and by when.
- Get quotes and submit them to the lender. The lender and appraiser need written quotes to approve purchase plus improvements.
- Close, renovate, release the holdback. The lawyer releases the money once the work is confirmed.
Frequently asked questions
Can I get a mortgage on a house with knob-and-tube wiring?
Often yes, but the home insurer is usually the obstacle. Many insurers will not cover active knob-and-tube, or require replacement within a set time. Lenders need insurance to fund, so get a quote early and consider financing the rewiring with a purchase-plus-improvements mortgage.
How much can I add for renovations with purchase plus improvements?
It depends on the lender and insurer. Many cap improvements as a share of the as-improved value and require written contractor quotes. In our Merritton example, $40,000 of electrical and plumbing work on a $485,000 home raised the payment by about $188 a month.
Do lenders finance homes with oil tanks?
Many do if the tank is above ground, in good condition and has an inspection certificate acceptable to the insurer. Buried or very old tanks raise environmental and insurance concerns, and some lenders and insurers require removal first.
Are wartime houses harder to finance?
Not usually. They are detached homes and are financed like any other house. The issues tend to be age-related: original wiring, small electrical panels, vermiculite insulation and older plumbing. The small size also limits some renovation plans, so check what an addition would require with the municipality.
Does a heritage designation affect my mortgage?
It rarely stops a mortgage, but designated properties and heritage districts can limit exterior changes and add approval steps for renovations. Your real estate lawyer can confirm designation, and the municipality can explain what changes need a permit.
Pre-approval & rate review
Get your Niagara mortgage numbers checked
Tell us where you are buying or what you owe. We reply by email, usually within one business day, with options from across the lender tiers.
- A licensed advisor reviews your numbers against A-lenders, Ontario credit unions and alternative lenders.
- Rate holds of up to 120 days on purchases and renewals (lender-dependent).
- On prime files the lender pays the brokerage, so there is no fee to you; any fee on alternative or private files is disclosed in writing first.
- Nothing goes to a lender or credit bureau until you say so.
Prefer email? Write to hello@mortgageniagara.com.