Niagara communities
Niagara-on-the-Lake Mortgage Broker
Old Town heritage homes, Virgil and St. Davids subdivisions, Queenston on the river and vineyards in between. NOTL has the region's highest benchmark and lowest tax rate. Here is the full cost at $865,000.
Reviewed November 13, 2026 · Indicative figures, OAC
Niagara-on-the-Lake by the numbers
- Benchmark price
- $865,000
- Property tax rate (approx.)
- 1.08%
- Minimum down at benchmark
- $61,500
- Ontario LTT at benchmark
- $13,775
Niagara-on-the-Lake sits where the Niagara River meets Lake Ontario, and it is the most expensive municipality in the region, with a composite benchmark of about $865,000. It also has the lowest approximate residential tax rate in Niagara, about 1.08%, or about $9,342 a year and $779 a month at the benchmark. The rate is an estimate; confirm it and your assessment with the Town of Niagara-on-the-Lake.
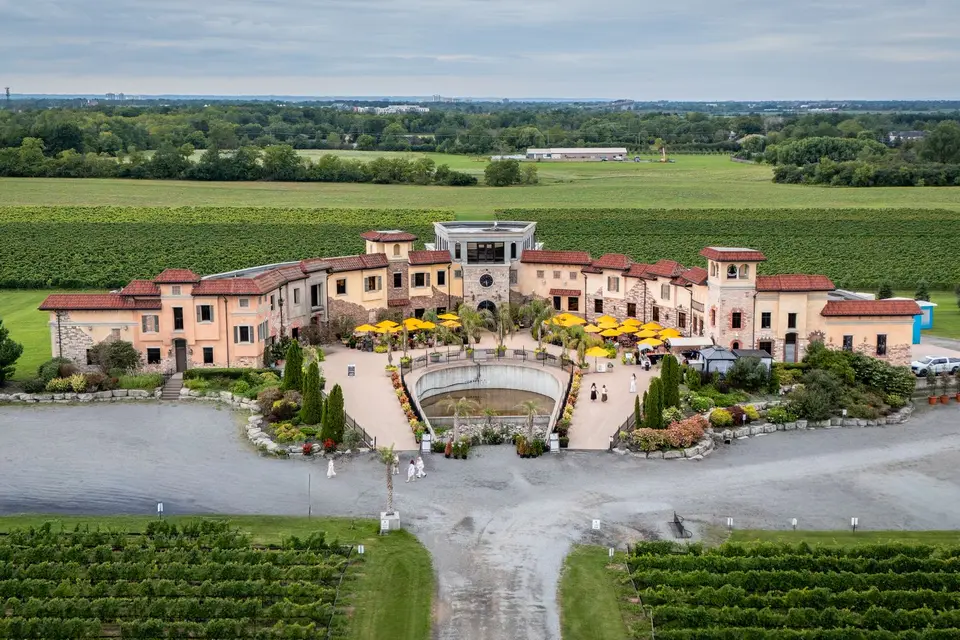
The town is made up of distinct communities: the Old Town with its heritage homes and Queen Street core; Virgil and St. Davids, with newer subdivisions and estate homes; Queenston at the foot of the escarpment on the river; and the farmland and vineyards that connect them. Niagara College's NOTL campus, with its wine and culinary programs, adds a small rental market of its own.
Who buys in NOTL
Downsizers and retirees
Many buyers are owners selling a bigger home elsewhere, often in the GTA, and buying here with substantial equity. Many need a smaller mortgage or none at all. The questions are usually about timing the sale and purchase, bridge financing, and whether to keep a line of credit available for later.
Move-up families
Virgil and St. Davids draw families buying their second or third home. At these prices the 10% portion of the minimum down payment adds up quickly, and many buyers aim for 20% to avoid the insurance premium.
Vineyard and rural buyers
Homes among the vineyards can be residential properties on a lot, or working farms. Lenders treat these very differently; see the rural section below.
High-value mortgages under $1.5 million
Default insurance is available on purchases up to $1.5 million, so even at NOTL prices a buyer can put less than 20% down. Above $1.5 million, 20% is the minimum and the mortgage is uninsured. Between those, the rate tier depends on your down payment:
- Under 20% down: insured, currently around 4.29% for a 5-year fixed (indicative, OAC), plus the premium and 8% PST on it.
- 20% or more down, purchase up to $1.5 million: insurable, around 4.39%, no premium to you.
- Over $1.5 million, or a refinance: uninsured, around 4.54%.
Our insured vs. insurable vs. uninsured guide explains why a smaller down payment can sometimes carry a lower rate.
Worked example: 20% down on an $865,000 home
With $173,000 down, the mortgage is $692,000 with no insurance premium or PST. At the insurable 4.39% the payment is about $3,788 a month over 25 years or $3,445 over 30 years. The stress test is applied at 6.39%, where the 25-year payment is about $4,589.
Equity, reverse mortgages and HELOCs
Many NOTL homeowners are house-rich and income-light in retirement. Two tools come up most:
- A reverse mortgage (age 55+, up to about 55% of the home's value, no payments required while you live in the home), offered by lenders such as HomeEquity Bank and Equitable Bank. See our reverse mortgage page.
- A HELOC, a revolving line secured on the home, which needs income to qualify but costs less. See the HELOC page.
Estate and tax implications are a question for your lawyer and accountant before you sign either.
Vineyards, rural services and short-term rentals
Outside the urban areas, some NOTL homes run on cisterns, wells and septic, and lenders want a potable water test and septic inspection. Many A-lenders value the home and up to about 10 acres, with little value for outbuildings, and an income-producing vineyard needs agricultural lending. Agricultural zoning and the Niagara Escarpment area near Queenston add planning checks. Read the vineyard and hobby farm guide and the rural services guide.
Short-term rentals and bed and breakfasts are licensed in Niagara-on-the-Lake; check the current town licensing by-law before buying with that plan. A-lenders generally will not count short-term rental income; some B-lenders and credit unions will with a 12 to 24 month history. See the short-term rental guide.
Closing costs and qualifying income at $865,000
Worked example: minimum down on an $865,000 NOTL home
Minimum down, 5-year insured fixed at 4.29% (indicative, OAC), property tax at about 1.08%, $125 a month for heating. Left: a repeat buyer of a resale home at 25 years. Right: a first-time buyer at 30 years with the land transfer tax refund.
| Item | Repeat buyer, 25 years | First-time buyer, 30 years |
|---|---|---|
| Purchase price | $865,000 | $865,000 |
| Minimum down payment (5% of $500,000 + 10% of $365,000) | $61,500 | $61,500 |
| Mortgage before insurance (92.89% loan-to-value) | $803,500 | $803,500 |
| Default insurance premium | 4.00% = $32,140 | 4.20% = $33,747 |
| Insured mortgage | $835,640 | $837,247 |
| 8% Ontario PST on premium (cash) | $2,571 | $2,700 |
| Ontario land transfer tax | $13,775 | $9,775 (after $4,000 refund) |
| Municipal land transfer tax | $0 | $0 |
| Legal, title insurance and disbursements (budget) | $1,850 | $1,850 |
| Cash needed on closing | $79,696 | $75,825 |
| Monthly principal and interest at 4.29% | $4,528 | $4,120 |
| Monthly property tax (about 1.08%) | $779 | $779 |
| Heating allowance | $125 | $125 |
| Monthly housing cost | $5,432 | $5,024 |
| Payment at the 6.29% stress-test rate | $5,491 | $5,133 |
| Household income needed at 39% GDS | $196,765 | $185,733 |
Income figures assume no other debts. Heritage homes in the Old Town may need specialized insurance and inspections; budget for them before you firm up.
Model your purchase in the payment and closing cost calculator. Nearby, compare St. Catharines and Niagara Falls.
Frequently asked questions
Can I buy an $865,000 home in Niagara-on-the-Lake with less than 20% down?
Yes. Default insurance is available up to a $1.5 million price. The minimum down payment at $865,000 is $61,500: 5% of the first $500,000 plus 10% of the remaining $365,000. The insurance premium is added to the loan, and the 8% PST on it is paid in cash at closing.
What is the property tax rate in Niagara-on-the-Lake?
Approximately 1.08%, the lowest in Niagara on our estimates, which is about $779 a month on an $865,000 home. Confirm the current rate and your assessment with the town.
Is a reverse mortgage a good idea for a NOTL retiree?
It can suit owners aged 55 or older who want to stay put without monthly payments, borrowing up to about 55% of the home's value. It costs more than a HELOC and reduces the equity left in the estate, so compare both and talk to your lawyer and family first.
Can I rent my NOTL home as a short-term rental to help qualify?
Short-term rentals are licensed in Niagara-on-the-Lake, so check the current by-law first. Most A-lenders will not count short-term rental income; some B-lenders and credit unions will once you have a 12 to 24 month history.
What does it cost to close at the NOTL benchmark?
With the minimum $61,500 down, a repeat buyer needs about $79,696: the down payment, $2,571 PST on the premium, $13,775 Ontario land transfer tax and about $1,850 in legal costs. There is no municipal land transfer tax in Niagara.
Pre-approval & rate review
Get your Niagara mortgage numbers checked
Tell us where you are buying or what you owe. We reply by email, usually within one business day, with options from across the lender tiers.
- A licensed advisor reviews your numbers against A-lenders, Ontario credit unions and alternative lenders.
- Rate holds of up to 120 days on purchases and renewals (lender-dependent).
- On prime files the lender pays the brokerage, so there is no fee to you; any fee on alternative or private files is disclosed in writing first.
- Nothing goes to a lender or credit bureau until you say so.
Prefer email? Write to hello@mortgageniagara.com.