Niagara property specialists
Condo and Townhouse Mortgages in Grimsby, St. Catharines and Fonthill
A condo can need less income to qualify than a freehold townhouse and still cost more every month. Here is how lenders treat condo fees, status certificates and small units across Niagara.
Reviewed November 13, 2026 · Indicative figures, OAC
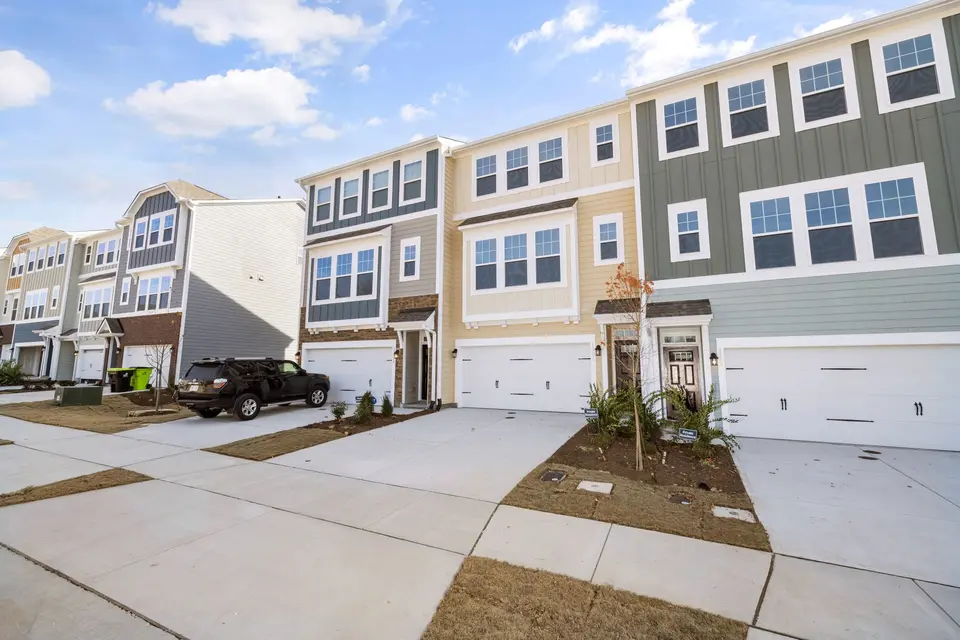
Three kinds of attached home
Niagara's attached housing ranges from the lakefront towers and mid-rises of Grimsby-on-the-Lake to apartment condos in downtown St. Catharines and Niagara Falls, and from stacked and row townhouses in Welland and Thorold to the newer townhouse streets of East Fonthill in Pelham. To a lender, they fall into three ownership types:
- Standard condominium: you own your unit plus a share of the common elements, and pay monthly fees to the condominium corporation, which maintains the building and saves into a reserve fund.
- Freehold townhouse: you own the house and the land outright, with no condo corporation and no monthly fee. Underwritten like a detached home.
- Common elements condominium (POTL): you own the townhouse and lot freehold, but share a private road, visitor parking or amenities through a small condo corporation with a modest fee. Common in newer Niagara subdivisions.
- Condo fees counted in GDS
- 50%
- Insured GDS / TDS limits
- 39% / 44%
- Grimsby approx. tax rate
- 1.15%
- Max insured LTV
- 95%
What lenders check on a condo
The status certificate
The condominium corporation's status certificate is the most important document in a resale condo purchase. It shows the monthly fee, whether the seller is in arrears, the reserve fund balance and the latest reserve fund study, any planned special assessments or fee increases, lawsuits involving the corporation, insurance coverage, and the rules (pets, rentals, short-term rentals). Your offer should be conditional on your lawyer's review of it. Lenders and insurers may ask questions if the reserve fund looks thin or there is a major lawsuit.
Fees in your ratios
Under insurer rules, 50% of the condo fee goes into your GDS ratio, alongside principal and interest, property tax and heat. The full fee is still a real monthly cost you pay.
Unit size and building type
Some lenders have minimum unit sizes, often somewhere around 500 to 600 square feet of living space, or treat micro-units and studios differently. Hotel-style condos, units in buildings with a rental pool, and units without a full kitchen are financed by a much smaller group of lenders. Niagara Falls has some tourist-oriented buildings where this matters, so check before you offer.
Rental concentration and commercial space
A building where a large share of units are tenant-occupied, or with significant commercial space, can narrow the lender list. The status certificate and the corporation's records usually show this.
New condos and occupancy
On a new condo, buyers often move in during an interim occupancy period before the building registers, paying the builder monthly occupancy fees (interest on the unpaid balance, estimated tax and the condo fee) that do not reduce the price. The mortgage funds at registration. If the appraisal at registration comes in low, see our pre-construction shortfall guide.
Condo vs. freehold townhouse: the numbers
Worked example: $520,000 Grimsby condo vs. $600,000 St. Catharines freehold townhouse
A first-time buyer compares a two-bedroom condo at Grimsby-on-the-Lake for $520,000 with a $620 monthly fee, against a freehold townhouse in St. Catharines for $600,000 with no fee. Both with 10% down, insured, 30-year first-time buyer amortization, at 4.29%. At exactly 90% LTV the premium is 3.10% plus the 0.20% 30-year surcharge, so 3.30%.
| Item | Grimsby condo | St. Catharines freehold town |
|---|---|---|
| Price | $520,000 | $600,000 |
| Down payment (10%) | $52,000 | $60,000 |
| Premium (3.30%), added to loan | $15,444 | $17,820 |
| PST on premium, cash at closing | $1,235.52 | $1,425.60 |
| Total mortgage | $483,444 | $557,820 |
| Monthly payment at 4.29% | $2,379 | $2,745 |
| Property tax (approx. 1.15% / 1.26%) | $498 | $630 |
| Condo fee | $620 | $0 |
| Real monthly cost (payment, tax, heat, fee) | $3,622 | $3,500 |
| Qualifying payment at 6.29% | $2,964 | $3,420 |
| GDS costs (with 50% of fee) | $3,897 | $4,175 |
| Income needed at 39% GDS | $119,912 | $128,455 |
The condo needs about $8,500 less income to qualify, because only half of the $620 fee counts. But it actually costs about $122 more a month than the townhouse that is $80,000 more expensive. The fee does cover things the townhouse owner pays separately (exterior maintenance, the roof, snow removal, building insurance), so the comparison is not apples to apples, but buyers should see both numbers.
Land transfer tax with the first-time buyer refund: $6,875 − $4,000 = $2,875 on the condo, and $8,475 − $4,000 = $4,475 on the townhouse. Niagara has no municipal land transfer tax.
Which lender tier fits
| Property | Usual fit |
|---|---|
| Freehold townhouse | Any A-lender; treated like a detached home |
| Standard condo, healthy reserves, typical size | Any A-lender, insured or conventional |
| POTL townhouse with small common-element fee | Most A-lenders; fee counted like a condo fee |
| Small or studio unit below some lenders' minimum | Selected A-lenders or a credit union, often with more down |
| Hotel-style or rental-pool condo | Very limited lenders, credit unions or B-lenders |
| Building with a major lawsuit or special assessment | Case by case; some lenders decline until resolved |
Run your own numbers, including condo fees, with the affordability and stress test calculator, and see how ratios work in the stress test and GDS/TDS guide.
Documents for a condo or townhouse purchase
- Status certificate (resale condo or POTL), reviewed by your lawyer.
- MLS listing showing square footage, parking and locker.
- Your income, down payment and debt documents.
- For new builds: the agreement of purchase and sale, the disclosure statement and the builder's occupancy terms.
Steps to buy a condo or townhouse in Niagara
- Get pre-approved with the fee included. Your maximum price depends on the fee. Start at pre-approval.
- Check the building before you fall for the unit. Size, rental mix and building type can rule out some lenders.
- Make the offer conditional on the status certificate. Your lawyer reviews it within the condition period.
- Compare the real monthly cost. Payment, tax, fee and utilities, not just the price.
- Close and keep the paperwork. The status certificate and the corporation's notices matter again at renewal or resale.
Frequently asked questions
How are condo fees counted in a mortgage application?
Under insurer rules, 50% of the monthly condo fee is added to your GDS ratio with principal and interest, property tax and heat. In our Grimsby example, a $620 fee added $310 to the qualifying costs, and the buyer needed about $119,912 of income at 39% GDS.
What is a status certificate and why does it matter?
It is a package from the condominium corporation showing fees, arrears, the reserve fund, planned special assessments, lawsuits, insurance and rules. Your lawyer should review it before your offer goes firm, because it can reveal costs that are not in the listing.
Is there a minimum size for a condo mortgage?
Some lenders set minimum living areas, commonly somewhere around 500 to 600 square feet, or treat studios and micro-units differently. Others are more flexible. Check before you make an offer on a very small unit.
Is a freehold townhouse easier to finance than a condo?
Usually, yes. A freehold townhouse has no condo corporation, status certificate or fee, so lenders treat it like a detached home. A common elements (POTL) townhouse is close to freehold but has a small fee and a status certificate.
Can I buy a Niagara condo with 5% down?
Yes, if you live in it and the price is under $1.5 million. The minimum is 5% of the first $500,000 and 10% of the rest, so $27,000 on a $520,000 condo, plus the default insurance premium and the 8% PST on it in cash at closing.
Pre-approval & rate review
Get your Niagara mortgage numbers checked
Tell us where you are buying or what you owe. We reply by email, usually within one business day, with options from across the lender tiers.
- A licensed advisor reviews your numbers against A-lenders, Ontario credit unions and alternative lenders.
- Rate holds of up to 120 days on purchases and renewals (lender-dependent).
- On prime files the lender pays the brokerage, so there is no fee to you; any fee on alternative or private files is disclosed in writing first.
- Nothing goes to a lender or credit bureau until you say so.
Prefer email? Write to hello@mortgageniagara.com.