Niagara communities
Welland Mortgage Broker
Welland is where many Niagara buyers get their first set of keys. At a $485,000 benchmark, here is the cash, the monthly cost and the income it takes, plus how new builds and Niagara College rentals are financed.
Reviewed November 13, 2026 · Indicative figures, OAC
Welland in four numbers
- Benchmark price
- $485,000
- Property tax rate (approx.)
- 1.32%
- Minimum down at benchmark
- $24,250
- Ontario LTT at benchmark
- $6,175
Welland sits in the middle of the peninsula, split by the Welland Canal and the old canal channel through downtown. With a composite benchmark of about $485,000, it is one of the few Niagara cities where the typical home is still under $500,000. That matters more than it sounds: below $500,000 the minimum down payment is a flat 5%, so the benchmark home needs just $24,250 down.
The trade-off is the property tax rate, approximately 1.32%, higher than St. Catharines or Niagara Falls. At the benchmark that is about $6,402 a year, or $534 a month. Rates are set each year and your bill depends on the MPAC assessment, so confirm with the City of Welland.
Neighbourhoods and what is on the market
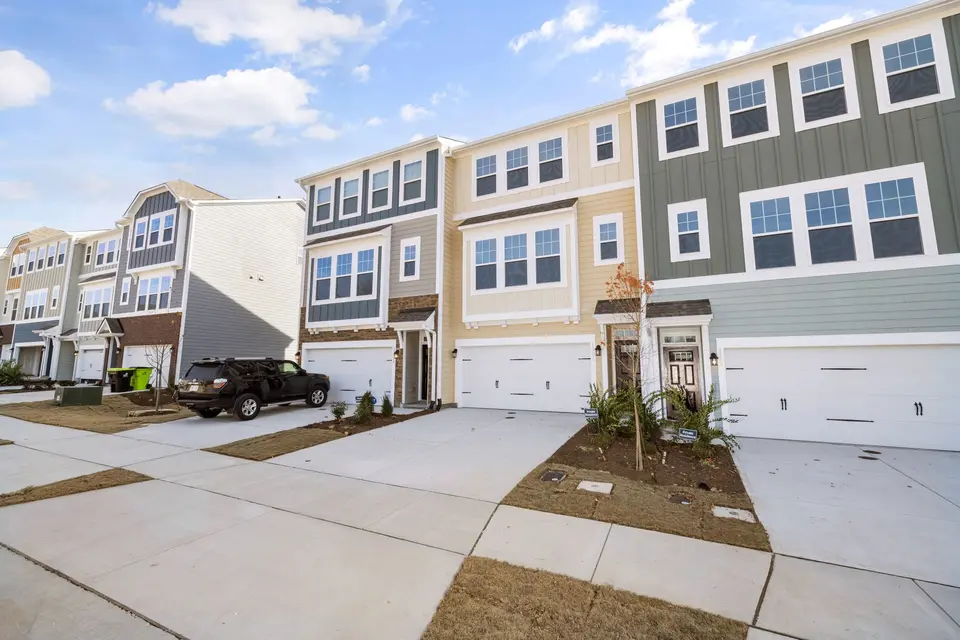
- Dain City, in the south end along the canal, is where much of Welland's newer subdivision building has happened. New detached homes and townhouses here draw first-time buyers and young families.
- The older core around downtown and both sides of the old canal has brick two-storeys, wartime homes and houses already split into two units, a staple for first-time investors.
- The north end near Niagara College's Welland campus has bungalows and backsplits, some rented to students.
- Edges of the city toward Pelham and Port Colborne include larger lots, some on private services, which brings in the rural questions covered below.
First-time buyers: why Welland pencils out
A first-time buyer at the Welland benchmark can combine three advantages. First, the 5% minimum down. Second, the 30-year insured amortization, available to every first-time buyer. Third, the Ontario land transfer tax refund of up to $4,000, which cuts the $6,175 tax to $2,175. Add the FHSA ($8,000 a year, $40,000 lifetime) and the RRSP Home Buyers' Plan (up to $60,000 each), and a couple can often build the down payment from tax-advantaged savings. Our first-time buyer guide walks through the order to use them in, and your accountant can confirm the tax side.
New builds in Welland
Buyers of newly built homes qualify for the 30-year insured amortization even if they are not first-time buyers. New homes also carry rebates: the federal first-time buyer GST rebate and Ontario's matching rebate of the provincial part of the HST can be substantial on homes up to $1 million. Confirm eligibility and timing with your real estate lawyer, because the builder's agreement of purchase and sale decides who receives the rebate.
The bigger risk with pre-construction is time. A home bought two years before closing is appraised at completion, and if the appraisal comes in below your purchase price, the lender lends on the lower figure and you cover the gap. Read our appraisal shortfall guide and the new-build mortgage page before signing.
Niagara College rentals and duplexes
Welland's student rental market follows the college. Lenders want legal bedrooms, meaning egress windows, smoke and CO alarms and fire separation where required, and will not finance an illegal rooming house. Many prefer a joint-and-several lease over room-by-room leases, and some cap the number of rentable bedrooms before treating the property as commercial. Zoning and rental rules apply, so check the current Welland by-law. On an A-lender file, typically 50% of the rent is added to your income or a rental offset is used.
Duplexes and houses with a legal second unit are the other common investment. Ontario allows up to three units on most serviced urban lots as of right, subject to local zoning and the Building and Fire Codes. See the student rental guide, the duplex and secondary suite guide, and the rental cash-flow calculator.
Closing costs and qualifying income at $485,000
Worked example: a $485,000 home in Welland
5% down, 5-year insured fixed at 4.29% (indicative, OAC), property tax at about 1.32%, $125 a month for heating. Left: a repeat buyer of a resale home, capped at 25 years. Right: a first-time buyer (or a new-build buyer) at 30 years; the land transfer tax refund applies to the first-time buyer only.
| Item | Repeat buyer, 25 years | First-time buyer, 30 years |
|---|---|---|
| Purchase price | $485,000 | $485,000 |
| Minimum down payment (5%) | $24,250 | $24,250 |
| Mortgage before insurance (95% loan-to-value) | $460,750 | $460,750 |
| Default insurance premium | 4.00% = $18,430 | 4.20% = $19,352 |
| Insured mortgage | $479,180 | $480,102 |
| 8% Ontario PST on premium (cash) | $1,474 | $1,548 |
| Ontario land transfer tax | $6,175 | $2,175 (after $4,000 refund) |
| Municipal land transfer tax | $0 | $0 |
| Legal, title insurance and disbursements (budget) | $1,850 | $1,850 |
| Cash needed on closing | $33,749 | $29,823 |
| Monthly principal and interest at 4.29% | $2,596 | $2,362 |
| Monthly property tax (about 1.32%) | $534 | $534 |
| Heating allowance | $125 | $125 |
| Monthly housing cost | $3,255 | $3,021 |
| Payment at the 6.29% stress-test rate | $3,149 | $2,943 |
| Household income needed at 39% GDS | $117,151 | $110,825 |
Income figures assume no car loan, student loan or card balances; those count against the 44% TDS limit. Closing cash excludes the inspection and adjustments.
Try your own numbers in the payment and closing cost calculator, or check your borrowing power in the stress-test calculator. Nearby, compare Thorold, Pelham and Fonthill and Port Colborne.
Frequently asked questions
What is the minimum down payment for a $485,000 home in Welland?
5%, or $24,250, because the price is under $500,000. With less than 20% down the mortgage is insured, and the 8% Ontario PST on the insurance premium (about $1,474 to $1,548) is paid in cash at closing.
How much land transfer tax will a first-time buyer pay in Welland?
The Ontario land transfer tax on $485,000 is $6,175. A first-time buyer gets up to $4,000 back, so the net cost is $2,175. Welland has no municipal land transfer tax.
Can I get a 30-year mortgage on a new build in Welland if I already own a home?
Yes. Since December 15, 2024, buyers of newly built homes qualify for a 30-year insured amortization whether or not they are first-time buyers. Repeat buyers of resale homes with less than 20% down remain at 25 years.
Will a lender finance a Niagara College student rental in Welland?
Yes, if the bedrooms are legal and the use fits the zoning. Lenders typically want egress windows, smoke and CO alarms and fire separation where required, and will not finance an illegal rooming house. Check the current Welland zoning and rental by-laws before you buy.
What is the property tax rate in Welland?
Approximately 1.32%, or about $534 a month on a $485,000 home. The actual bill depends on your MPAC assessment and the year's rates, so confirm with the City of Welland.
Pre-approval & rate review
Get your Niagara mortgage numbers checked
Tell us where you are buying or what you owe. We reply by email, usually within one business day, with options from across the lender tiers.
- A licensed advisor reviews your numbers against A-lenders, Ontario credit unions and alternative lenders.
- Rate holds of up to 120 days on purchases and renewals (lender-dependent).
- On prime files the lender pays the brokerage, so there is no fee to you; any fee on alternative or private files is disclosed in writing first.
- Nothing goes to a lender or credit bureau until you say so.
Prefer email? Write to hello@mortgageniagara.com.